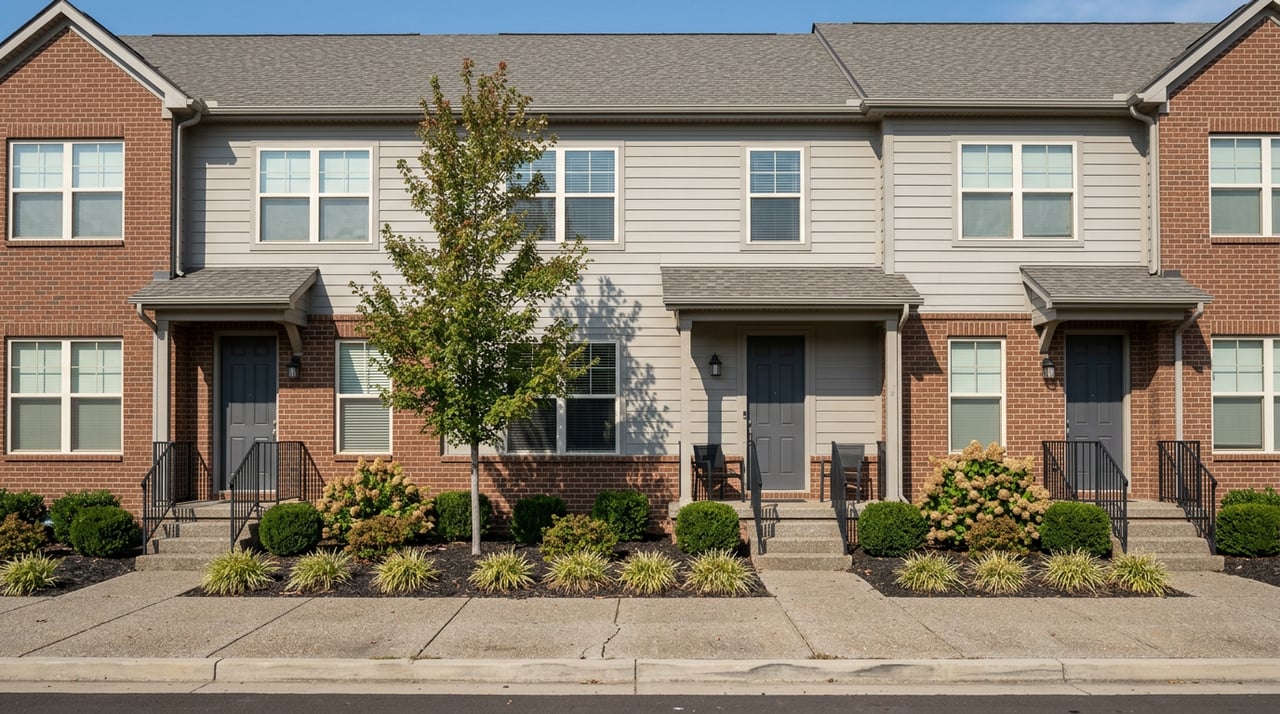
Thinking about a simpler, lower‑maintenance home in Wyandotte County? Townhomes and condos can offer the space you need without the weekend yard work and big exterior surprises. If you are buying your first home or planning a smart downsize, understanding floor plans, HOA costs, and financing will help you choose with confidence. This guide breaks down what you will find locally, how to read an HOA, and where these homes tend to cluster. Let’s dive in.
Quick market snapshot
Wyandotte County has a diverse housing mix with an owner‑occupancy rate around 62 percent, according to U.S. Census QuickFacts. Attached homes like townhomes and condos are a smaller but meaningful slice of the market. Local planning data shows single‑unit attached housing sits in the single‑digits percentage range of the county’s total units, which means choice is available but inventory can be limited compared with detached homes. You can review county mix context in the Bonner Springs Housing Needs Analysis.
As of March 2026, public market snapshots often place the typical home value in the roughly 190,000 to 200,000 dollar range. Actual prices vary by location, size, age, and HOA amenities, and they change monthly. Much of the county’s housing stock is older, with pockets of newer townhome construction in the western corridor and infill options closer to downtown Kansas City, KS.
What you will find
Low‑rise condos and lofts
You will see 1 to 2 bedroom condos, often about 500 to 1,200 square feet, in older garden‑style buildings and some adaptive‑reuse lofts near downtown KCK and the riverfront. These can be among the most affordable ownership options and appeal if you want a walkable lifestyle and a smaller footprint. Tradeoffs often include limited private outdoor space and a mix of on‑site or street parking.
Condo associations usually carry a master insurance policy on the building, while you carry an HO‑6 policy for interior finishes and contents. To understand who covers what and where deductibles apply, review the master policy summary and your HO‑6 options. For a plain‑English overview of typical condo coverage, see this condo insurance and HOA coverage explainer.
Newer suburban townhomes
Western Wyandotte County and the Bonner Springs corridor feature more recent townhome communities with 2 to 3 bedrooms, attached garages, and two‑level floor plans around 1,200 to 1,800 plus square feet. HOAs in these areas often handle exterior maintenance, lawn care for common areas, and snow removal. In some communities the HOA also insures exterior elements. In others, owners insure the structure and the HOA maintains only shared spaces. The community declaration and rules set these details.
If you are comparing options, ask specifically about roofs, siding, driveways, and yard maintenance. The split of responsibilities can affect both your monthly dues and your long‑term costs.
Match plans to your goals
- First‑time buyers often prioritize value and predictable costs. Smaller condos or competitively priced new townhomes can provide modern systems and a garage at a lower entry price than many detached homes nearby.
- Downsizers usually want less maintenance and a lock‑and‑leave feel. Look for single‑level layouts or main‑level owner suites, accessible entries, reasonable HOA rules, and reliable parking for yourself and guests. For a quick primer on condo cost tradeoffs compared with single‑family homes, review this consumer guide on condo vs single‑family costs.
What HOAs cover and why it matters
Kansas gives owners certain rights in common‑interest communities under the Kansas Uniform Common Interest Owners’ Bill of Rights Act. The statute outlines open meeting practices, owner voting, and access to records. Before you buy, it is smart to know your rights and what to expect from an association. You can read the statute summary here: Kansas KUCIOBORA overview.
Associations must adopt budgets and keep records available for owner review. Kansas law does not set a required reserve‑fund level, so reserve planning varies by HOA. A strong reserve plan reduces the risk of sudden special assessments. For a practical look at reserve planning in Kansas, see this reserve study and board duties overview.
Your due‑diligence checklist
Request the association’s disclosure packet early and review it carefully. Ask for:
- Declaration, bylaws, and current rules and regulations. See Kansas HOA document basics in this state HOA overview.
- Most recent annual budget, year‑to‑date financials, and current reserve balance, plus any recent reserve study. Here is a Kansas reserve fund explainer.
- Minutes of recent board meetings and recent owner communications that mention maintenance projects or policy changes. Guidance on required records appears in the Kansas HOA overview.
- Certificate of insurance or master policy summary and the master policy deductible. For what is typically covered, review this condo coverage explainer.
- A resale certificate showing current dues, special assessments, and any pending legal matters. This document confirms the financial standing of the unit and the association.
Tip: Ask the HOA about historical special assessments and the plan for near‑term capital projects. If reserves are low, plan your budget accordingly.
Financing basics
Some mortgages require project‑level approvals. FHA, VA, and conventional loans sold to Fannie Mae or Freddie Mac may have condo project criteria that affect your loan options. If a project is non‑warrantable or not approved, you may need a different loan product or a single‑unit approval, which can add time and conditions. Learn the basics in this overview of FHA condo approvals and single‑unit approvals.
Lenders also review HOA reserves, insurance, and owner‑occupancy levels. High delinquency rates or low reserves can make financing harder and may affect resale value. Condo buyers should also carry an HO‑6 policy for interior coverage and be sure it coordinates with the master policy. For a refresher on coverage roles, revisit the condo coverage explainer.
How to stay on track:
- Ask your lender to check the project’s approval status before you write an offer.
- Build time into your contract for the HOA questionnaire and document review.
- If you need FHA or VA financing, verify project eligibility early.
Where to look in Wyandotte County
Downtown KCK and nearby neighborhoods
Areas near downtown Kansas City, KS, including Strawberry Hill and adjacent districts, offer older low‑rise condos and some loft conversions near dining, services, and quick access to downtown Kansas City, MO. Local housing organizations are active in these neighborhoods, as noted by community housing initiatives in Wyandotte County.
Western Wyandotte and Bonner Springs corridor
Farther west, you will find more recent townhome communities, small subdivisions, and builder models with garages and efficient footprints. This corridor often draws first‑time buyers and downsizers who want newer systems and lower exterior maintenance. For supply and growth context in this area, review the Bonner Springs Housing Needs Analysis.
Cost reality check
HOA dues vary widely. Some fee‑simple townhome neighborhoods charge modest annual dues for common areas, while condo buildings with shared amenities can run several hundred dollars per month. What you pay depends on the age of the building, services included, and long‑term reserve planning. For a simple overview of how HOA services affect monthly costs, see this condo vs single‑family cost guide.
When you compare homes, look at total monthly cost, not just list price:
- Mortgage principal and interest
- Property taxes
- HOA dues
- Unit insurance (HO‑6 for condos) and any required coverage add‑ons
- Utilities and internet if not included in dues
- A routine maintenance allowance
Next steps
If townhome or condo living sounds right for you, here is a simple game plan:
- Get pre‑approved and share any HOA or condo plans with your lender.
- Tour a mix of floor plans in your target areas to compare space, storage, parking, and noise levels.
- Before waiving contingencies, request the full HOA packet, including budget, reserves, insurance, minutes, and any upcoming projects.
- Confirm with your lender that the project meets loan requirements or discuss a single‑unit approval if needed.
- Price in HOA dues and reserves alongside your mortgage to see the true monthly picture.
Ready to map out options in Wyandotte County and compare HOA pros and cons? Reach out to Robert Kristi Porter for local guidance, vetted lender introductions, and curated townhome and condo tours.
FAQs
Are townhomes and condos cheaper than single‑family homes in Wyandotte County?
- Often the purchase price is lower, but your total monthly cost depends on HOA dues, insurance, taxes, and utilities. Compare the all‑in monthly budget for each property.
Will my lender approve a condo in Wyandotte County?
- Ask early about FHA, VA, or conventional project approval, or whether a single‑unit approval is possible. See this overview of FHA condo approval basics.
What should I verify in an HOA packet before buying?
- Review the CC&Rs, bylaws, rules, budget, reserves, recent board minutes, master insurance summary, and any special assessments or litigation. The Kansas HOA overview outlines key documents.
What insurance do I need for a condo or townhome?
- Most condo owners carry an HO‑6 policy for interior finishes and contents that aligns with the association’s master policy. Learn typical coverage splits in this condo insurance explainer.
How common are townhomes and condos in Wyandotte County?
- They represent a smaller but important part of the housing stock, with single‑unit attached housing in the single‑digits percentage range countywide. See the Bonner Springs Housing Needs Analysis for context.